
The New Economy Forum: How AI Is Reshaping Money, Work and Government
At the October 2026 IMF meetings in Bangkok, the New Economy Forum examined how artificial intelligence, digital financial infrastructure and new forms of taxation could change the global economy. The discussions raised a fundamental question: how can governments and businesses benefit from technological progress without increasing inequality, weakening financial stability or leaving workers behind?
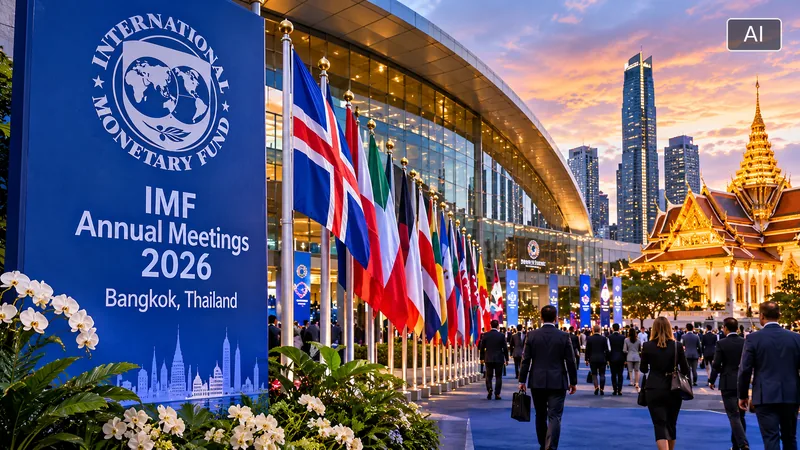
Artificial intelligence is no longer simply a subject for technology companies and research laboratories. It is becoming an economic issue that governments, central banks, financial institutions and businesses must address.
That was the underlying message of the New Economy Forum at the International Monetary Fund's October 2026 Annual Meetings in Bangkok.
The forum brought together specialists from financial institutions, technology companies, public authorities and academia to examine how technology is changing the way money moves, businesses operate and governments collect revenue.
Two subjects were particularly prominent: the combination of tokenisation and agentic artificial intelligence in financial infrastructure, and the challenge of designing tax systems for an economy in which machines may increasingly perform tasks previously carried out by people.
The wider programme also included discussions of AI-driven productivity, employment, financial stability and cybersecurity.
These are not separate developments. They are connected parts of a wider transformation.
If AI systems can perform more work, businesses may change how they employ people. If financial transactions become increasingly automated, the infrastructure supporting money and markets will need to evolve. If economic value shifts from labour towards capital, governments may need to reconsider how they collect taxes and finance public services.
The consequences will reach far beyond the technology sector.
Bangkok: a forum focused on the practical economy
The IMF and World Bank Annual Meetings took place in Bangkok from 12 to 18 October 2026.
The New Economy Forum was organised as a series of interactive panels and workshops examining the role of technology in modern economies.
The official programme included two central sessions:
- 13 October — New Trends in Financial Infrastructure: Tokenization and Agentic AI.
- 14 October — Rethinking Taxation for the AI Era.
A related workshop on 13 October examined how governments can connect tax collection and public spending systems through digital infrastructure.
The wider Annual Meetings programme extended the discussion. On 16 October, a high-level session titled AI and the Global Economy: From Risk to Opportunity was held. Participants listed in the official programme included Anthropic co-founder Jack Clark, Bank of Canada Governor Tiff Macklem and DHL Group Chief Executive Tobias Meyer.
A separate session examined the implications of AI for cybersecurity and financial stability, with representatives from the Bank for International Settlements, Switzerland's financial regulator FINMA, Brazil's central bank and Anthropic.
The programme shows that the IMF was not treating AI as a narrow technology subject. It was examining the implications for monetary and financial systems, employment, taxation, competition and economic policy.
Agentic AI: when software begins to act
One of the most important concepts discussed in Bangkok was agentic AI.
Traditional digital tools generally respond to instructions. A person enters information, requests an action or selects an option, and the software performs a defined task.
Agentic AI goes further.
An AI agent can be given an objective, interpret information, plan a sequence of actions and carry out parts of a task with less continuous human direction. Depending on the system and permissions granted, it may interact with other software, retrieve information, make decisions within defined limits and execute transactions.
For example, an AI agent working for a business might monitor incoming orders, check stock availability, compare supplier prices, prepare purchase orders and arrange deliveries.
In financial services, an agent could compare payment providers, assess exchange rates, check liquidity requirements and select an appropriate route for a transaction.
In a more advanced system, several agents could interact with one another. A purchasing agent might negotiate with a supplier's system, while another agent checks payment terms and a third monitors compliance requirements.
This could change the economics of business operations.
Tasks that currently require several employees, separate software systems and repeated administrative steps may become faster and less expensive.
However, the ability to act also creates a different category of risk.
An AI system that provides incorrect information can mislead a user. An AI agent with permission to transfer money, change records or enter agreements can potentially cause direct financial damage.
Businesses and financial institutions will therefore need clear rules governing:
- What an AI agent is allowed to do.
- Which transactions require human approval.
- How identity and authority are verified.
- How actions are recorded and audited.
- What happens when an agent makes an error or behaves unexpectedly.
- Who is legally responsible for its actions.
The IMF's September 2026 analysis of AI and payments policy argues that agentic systems could automate complex financial transactions and reduce the cost of compliance and reporting. It also stresses that existing payment systems may be upgraded to deliver many early benefits without requiring an entirely new financial architecture.
The important point is that agentic AI is not simply a better chatbot. It introduces software that can participate in economic activity by taking actions on behalf of people and organisations.
Tokenisation: changing how financial assets are held and transferred
The second major subject was tokenisation.
Tokenisation means representing a financial asset or claim digitally on a programmable ledger, often using distributed ledger technology.
An asset could be a bond, fund holding, financial contract or other recognised claim. Instead of relying entirely on separate systems for issuance, trading, ownership records and settlement, tokenisation can allow some of these functions to operate through connected digital infrastructure.
The potential advantages include:
- Faster settlement.
- More continuous trading.
- Greater transparency in ownership and transaction records.
- Reduced reconciliation between institutions.
- Fractional ownership of assets.
- More automated collateral and liquidity management.
In theory, a financial transaction could become much more integrated. The asset, payment and contractual conditions could interact through programmable systems, reducing the number of separate steps required.
This was the subject of the 13 October New Economy Forum session, which brought together representatives from the IMF, Standard Chartered, the Monetary Authority of Singapore, Euroclear and Swift.
The panel was designed to explore how tokenisation and agentic AI could affect settlement, collateral, liquidity optimisation, cross-border transactions and interoperability.
The market is developing, but it remains small
The IMF's October 2026 Global Financial Stability Report provides an important reality check.
Tokenised financial markets are growing, but they remain small compared with traditional financial markets and are fragmented across different platforms.
The IMF estimates that tokenised repurchase agreements account for approximately $300 billion to $350 billion in daily transaction volume. Other tokenised assets, including credit, money-market funds and equities, add approximately $65 billion in daily transaction volume.
For comparison, the US repurchase agreement market handles around $13 trillion in daily activity, while global capital markets represent approximately $300 trillion in assets.
These figures show both the potential and the distance still to travel.
Tokenisation is not yet replacing traditional financial markets. It is developing alongside them.
The IMF identifies four important conditions for wider adoption:
Legal certainty: Investors need to know exactly what rights they own when they hold a tokenised asset.
Regulatory clarity: Existing financial rules must be applied consistently, regardless of whether an asset is recorded on a conventional database or a distributed ledger.
Interoperability: Different platforms must be able to communicate and exchange assets. Otherwise, markets may become isolated pools of liquidity.
Reliable settlement assets: Transactions need access to safe and widely accepted forms of money.
The IMF also warns that tokenised markets currently exhibit relatively low liquidity and higher volatility than their traditional counterparts. Fragmentation can make it difficult to establish reliable prices and move assets efficiently between platforms.
The technology may remove some existing frictions, but it does not automatically remove financial risk.
Faster settlement can create new pressures
One particularly important issue is liquidity.
Traditional financial transactions often involve time between agreement, confirmation and final settlement. That process can create delays and administrative costs, but it also provides institutions with time to manage their cash and liquidity positions.
Tokenised systems may allow transactions to settle almost instantly.
That can reduce counterparty risk — the possibility that one party fails to complete its side of a transaction. But immediate settlement can also require participants to have sufficient funds available at the exact moment a transaction takes place.
The IMF therefore warns that the transition to faster settlement could increase intraday liquidity requirements.
In other words, making financial transactions faster does not necessarily make the entire financial system safer.
Taxation: who pays when machines do more of the work?
The second major New Economy Forum session addressed a question that governments cannot avoid indefinitely:
How should governments collect tax revenue when the balance between human labour and automated production changes?
Most modern tax systems depend heavily on economic activity generated by people and businesses.
Governments collect taxes on wages, consumption, profits, property and other forms of economic activity. Payroll taxes and social contributions are particularly important in financing pensions, healthcare and other public services in many countries.
If AI increases productivity while reducing the need for certain categories of labour, the relationship between economic output and tax revenue could change.
A company might produce more with fewer employees. Its profits could increase even as the wage bill grows more slowly.
That would not automatically cause a decline in government revenue. Corporate profits and consumption could generate additional tax receipts. But it could change where economic value is created and which parts of the tax system capture it.
The 14 October forum, Rethinking Taxation for the AI Era, brought together Adrian Brown of Windfall Trust, University of Pennsylvania professor Ioana Marinescu, tax law professor Miranda Stewart of NYU and Ruud De Mooij, Deputy Director of the IMF Fiscal Affairs Department.
The official programme identified several questions for discussion:
- Where should profits made by large technology companies be taxed?
- Should tax systems place different weight on labour and capital?
- Should governments consider special levies on computing capacity, energy used by AI systems or AI subscriptions?
- How can governments raise revenue and address inequality without discouraging innovation and technological adoption?
These were questions for debate, not an announcement of a new international AI tax.
Should governments tax AI directly?
One possible approach is to introduce a specific tax on AI-related activity.
Governments could consider levies on computing resources, energy consumption or certain AI services.
The argument in favour is that large-scale automation may generate substantial economic value while placing pressure on traditional sources of tax revenue.
However, a poorly designed tax could also discourage investment, slow the adoption of useful technology or place smaller businesses at a disadvantage.
A tax on computing capacity, for example, could affect a small company using cloud services just as it affects a major technology business, even though their financial resources and ability to absorb additional costs are very different.
There is also a practical problem: defining precisely what should be taxed.
AI is increasingly embedded in ordinary software and business services. A separate tax on every product or service using AI could become difficult to administer and create uncertainty for companies.
The wider policy challenge is therefore not simply to find a new tax base. It is to ensure that the tax system remains fair, effective and capable of financing public services as the economy changes.
The IMF's wider tax recommendations
The IMF's October 2026 Fiscal Monitor provides important context.
Its special-edition chapter, Taxing Better to Boost Growth, argues that governments can improve tax systems without necessarily increasing overall tax revenue.
The report focuses on reducing distortions that discourage investment, employment and productivity.
It identifies several areas for reform:
- Making VAT systems more neutral by ensuring businesses can properly recover tax paid on inputs.
- Improving corporate tax treatment of investment costs.
- Strengthening incentives to enter employment and work additional hours.
- Targeting public support for innovation more effectively.
- Modernising tax administration and simplifying compliance.
The report estimates that certain reforms could produce significant economic gains. For example, its modelling suggests that restoring VAT neutrality could generate welfare gains of up to 0.8% of GDP in the economies studied. Revenue-neutral reforms to employment taxation could raise employment rates by 0.8 percentage points in advanced economies and 1.2 percentage points in emerging-market and developing economies.
These are model-based estimates for selected economies, not guaranteed outcomes for every country.
The broader message is that governments should examine how their existing tax systems influence investment, employment and innovation before simply adding new taxes to emerging technologies.
Employment: the transition is already uneven
The consequences of AI for employment are among the most sensitive issues in the debate.
There are two competing possibilities.
AI can make workers more productive by helping them complete tasks faster, improve the quality of their work and access information more efficiently.
But AI can also perform tasks that previously required employees, potentially reducing the demand for certain skills and occupations.
The IMF has repeatedly warned that the impact will vary considerably between countries and types of work.
Its earlier global analysis estimated that almost 40% of employment worldwide is exposed to AI. In advanced economies, the proportion rises to approximately 60%, reflecting the greater prevalence of jobs involving cognitive tasks.
Exposure does not mean that a job will disappear. It means that AI could affect the tasks involved.
Some occupations may be strengthened because workers use AI to perform their jobs more effectively. Others may face a greater risk of automation.
Evidence from the workplace
Independent research provides a more detailed picture of what is happening.
The Stanford Institute for Human-Centered AI's 2026 AI Index reports that AI adoption among surveyed organisations reached 88% in 2025. Generative AI was being used in at least one business function by 70% of organisations.
However, the report also finds that the deployment of AI agents remained in the single digits across nearly all business functions.
This distinction is important: widespread use of AI tools does not mean that most companies have already handed substantial operational authority to autonomous agents.
The Stanford report also examines measured productivity gains.
Research cited in the report found that customer-support workers using generative AI resolved approximately 14–15% more issues per hour. One software-development study found a 26% increase in completed pull requests, while research on AI-assisted marketing reported a 50% increase in output per worker.
These results are encouraging, but they should not be interpreted as universal productivity improvements.
The gains are strongest in structured tasks where output can be measured and quality can be monitored. Other research has found that AI assistance can make some complex tasks slower or produce learning difficulties when workers rely too heavily on automated answers.
The technology's value depends on the task, the worker, the quality of the system and how it is introduced into the organisation.
Young workers may face an early warning
A particularly important study comes from Stanford's Digital Economy Lab.
In an August 2026 revision of its research paper Canaries in the Coal Mine?, researchers Erik Brynjolfsson, Bharat Chandar and Ruyu Chen analysed high-frequency payroll data covering millions of US workers through June 2026.
They found no evidence of widespread economy-wide job displacement.
However, employment among workers aged 22–25 in occupations highly exposed to AI was approximately 19% below the level it would have reached if it had kept pace with employment in less-exposed occupations.
The researchers found that the difference was driven mainly by reduced hiring of young workers, rather than a large increase in dismissals.
They also stressed that the findings are early descriptive indicators, not proof that AI alone caused the employment gap. The results are based on a particular payroll dataset and should not be treated as a direct forecast for other countries.
Nevertheless, they raise an important question.
If businesses use AI to perform entry-level tasks that traditionally helped young employees gain experience, how will the next generation develop the skills needed for more senior roles?
The issue may not be limited to job losses. It could also involve fewer opportunities to enter a profession in the first place.
Productivity: the promise is larger than automation
Productivity is the central economic reason governments and businesses are investing in AI.
If a company can produce more goods or services with the same number of employees, or maintain output with fewer resources, productivity rises.
Higher productivity can support economic growth, improve competitiveness and potentially create room for higher wages and better living standards.
But the gains do not happen automatically.
Businesses need to redesign processes, train employees, update information systems and establish reliable ways of checking AI-generated work.
An organisation that simply adds AI software to inefficient procedures may achieve little improvement.
The IMF's Managing Director, Kristalina Georgieva, addressed this issue in an October 15 article, The World Can't Afford to Get AI Wrong.
She argued that AI investment could eventually deliver a substantial positive supply shock, potentially raising global growth by around half a percentage point annually over the next decade.
That is a possible long-term gain, not a guaranteed forecast. It depends on whether investment translates into widespread adoption and lasting productivity improvements.
The Stanford research reinforces the need for caution. Measurable gains are emerging in some types of work, but results differ substantially between tasks and industries.
For businesses, the practical question is not how many AI subscriptions they purchase. It is whether the technology improves output, quality, costs or customer service in a measurable way.
Financial stability: a technology boom can become a financial risk
The AI transformation is also changing investment markets.
Large technology companies are spending heavily on data centres, advanced computing infrastructure, chips and energy systems.
The scale of investment is creating opportunities for suppliers, construction companies, utilities and technology businesses.
However, it also raises questions about market concentration, debt and investor expectations.
In her October 15 article, Georgieva warned that the AI ecosystem is becoming highly concentrated and that some investment relationships involve companies financing businesses that then purchase computing capacity from those same companies.
Such arrangements can create interconnected financial exposures.
If AI revenues disappoint or expected productivity gains fail to materialise, investors may reassess the value of companies and infrastructure projects.
A correction in technology markets could then affect lenders, investment funds and financial institutions exposed to the same assets.
The IMF's October Global Financial Stability Report also warns that strong investor confidence should not be confused with an absence of risk.
The report identifies AI-related market corrections, higher bond yields and cyber threats as potential sources of financial stress.
The concern is not that AI investment is necessarily a bubble. It is that expectations, financing structures and market valuations could become vulnerable if the economic returns fail to match the scale of investment.
For governments and financial regulators, the priority is to monitor concentration, leverage and the connections between technology companies and the wider financial system.
Cybersecurity: when AI accelerates both defence and attack
The more digital and interconnected the economy becomes, the more important cybersecurity becomes.
AI can help organisations identify suspicious activity, analyse large volumes of information and respond to threats more quickly.
But the same technology can also help criminals create convincing fraudulent messages, automate attacks, discover vulnerabilities and manipulate people into authorising payments.
The IMF's October 16 session on Artificial Intelligence and Escalating Cyber Risks examined the implications for macroeconomic and financial stability.
Panellists included FINMA Chair Marlene Amstad, BIS Deputy General Manager Andrea Maechler, Central Bank of Brazil Deputy Governor Paulo Picchetti and Anthropic's Head of Global Affairs Michael Sellitto.
The IMF's wider analysis warns that AI can compress the time between discovering a vulnerability and exploiting it.
This creates pressure on financial institutions, which must be able to detect and respond to threats at increasingly high speed.
A cyber incident affecting an ordinary business can cause financial losses and operational disruption. An incident affecting a critical financial institution, payment network or major technology provider could have consequences far beyond one company.
The Bangkok Blueprint
The meetings also saw the launch of the Bangkok Blueprint for Fraud-Resilient Financial Services, launched by the IMF and the World Bank together with the Bank of Thailand.
The framework addresses the growing problem of cyber-enabled fraud and the need for cooperation across the wider digital economy.
Its central argument is that financial institutions cannot tackle the problem alone.
Fraud often begins outside the banking system, through social media, messaging platforms, telecommunications services, online marketplaces and other digital channels. Victims may be manipulated into making payments themselves, rather than simply having money stolen without their knowledge.
The Blueprint therefore calls for a coordinated response involving financial regulators, banks, payment providers, technology platforms, telecommunications companies and law enforcement.
It also highlights the need for stronger consumer protection, cybersecurity, information sharing and clear responsibilities between institutions.
The framework is not a binding international law or a universal regulatory requirement. It is a policy blueprint intended to guide governments and industry as they develop national approaches.
Its publication demonstrates that the financial system's digital transformation is also a question of public trust.
People must be confident that their money, personal information and access to essential services remain protected.
What governments must prepare for
The discussions in Bangkok point towards several responsibilities for governments.
First, education and workforce preparation. Schools, universities and vocational programmes need to equip people with the technical, analytical and communication skills required in workplaces where AI is widely used.
Second, modern public infrastructure. Reliable digital networks, electricity supplies, data systems and secure payment infrastructure are essential if businesses and public institutions are to adopt new technology.
Third, tax reform. Governments need to monitor how AI affects wages, profits, investment and public revenue. They should avoid rushed measures that discourage useful innovation while ensuring that taxation remains fair and sustainable.
Fourth, financial regulation. Authorities must understand how tokenised assets, automated payments, AI agents and new financial intermediaries interact with existing systems.
Fifth, cybersecurity and consumer protection. Governments need the capacity to respond to increasingly sophisticated fraud and attacks on critical infrastructure.
There is also an international dimension. Digital financial markets and AI systems do not stop at national borders. Inconsistent rules can create gaps in supervision and opportunities for regulatory arbitrage.
Cooperation between governments and international institutions will therefore be essential.
What businesses should take from the transformation
For businesses, the message is practical.
AI can help companies reduce administrative work, improve customer service, analyse information, manage stock, develop products and operate more efficiently.
Smaller businesses may benefit particularly from access to tools that were previously available only to organisations with large technical departments.
However, successful adoption requires more than purchasing software.
Companies need to identify tasks where AI can produce measurable improvements, protect confidential information, train employees and establish clear rules for human oversight.
Financial and operational systems require particular care. An AI agent should not automatically receive unrestricted authority to transfer funds, change contractual arrangements or access sensitive information.
Businesses should also consider whether their dependence on a single AI provider or cloud platform creates operational risks.
The companies most likely to benefit will not necessarily be those that adopt the largest number of tools. They will be those that understand where technology adds value and integrate it responsibly into their operations.
The future of work: adaptation will determine who benefits
The economic transformation discussed in Bangkok will not affect everyone in the same way.
Some workers will use AI to become more productive and move into higher-value roles. Others may find that parts of their jobs are automated or that employers require fewer people for certain tasks.
Young people entering the labour market may face particular difficulties if traditional entry-level work becomes less available.
At the same time, new occupations and industries may emerge around AI development, infrastructure, security, data management and the integration of automated systems into existing businesses.
The speed of this transition will vary across countries and industries.
The IMF's message is that governments should prepare workers for change rather than assume that the labour market will adjust without support.
Training, active employment policies and effective social safety nets will matter. So will the ability of businesses to create new roles and use technology to expand economic activity rather than simply reduce costs.
A new economic system is taking shape
The New Economy Forum did not announce a single new global economic model or a universal regulatory solution.
Instead, it brought together several developments that are increasingly connected.
Agentic AI could allow software to carry out economic tasks and transactions. Tokenisation could change how assets are issued, held and transferred. Businesses may become more productive, but some forms of employment could come under pressure. Governments may need to rethink taxation, while financial regulators face new questions about market stability and cybersecurity.
The opportunities are substantial, but so are the responsibilities.
The central challenge is to ensure that technological progress produces lasting economic benefits rather than concentrating wealth, weakening public finances or creating new vulnerabilities in the systems on which society depends.
For governments, the task is to build the rules and infrastructure that allow innovation while protecting the public interest.
For businesses, it is to use technology intelligently, securely and productively.
For workers, it is to adapt to changing tasks and acquire skills that remain valuable as automation expands.
The transformation is already under way. The decisions made now will help determine who benefits from it — and who is left trying to catch up.
Sources
- IMF — 2026 Annual Meetings Schedule and Programme – Primary source for the dates, titles, descriptions and participants of the New Economy Forum sessions and related AI discussions.
- IMF — New Trends in Financial Infrastructure: Tokenization and Agentic AI, 13 October 2026 – Official description of the forum session and its participants from the IMF, Standard Chartered, Monetary Authority of Singapore, Euroclear and Swift.
- IMF — Rethinking Taxation for the AI Era, 14 October 2026 – Official description of the taxation session, including the questions raised about technology profits, labour and capital taxation, and possible levies on computing, energy and AI subscriptions.
- IMF — What Is Needed for Tokenization to Deliver, 8 October 2026 – IMF analysis of tokenised financial markets, their current scale, fragmentation, liquidity and regulatory requirements.
- IMF — Global Financial Stability Report, October 2026, Chapter 3: Scaling Tokenization: New Efficiencies, New Vulnerabilities – Detailed analysis of the benefits and risks of tokenised financial markets.
- IMF — AI and the Future of Payments Policy, 28 September 2026 – Analysis of agentic AI in payments, automated transactions, tokenised settlement, legal questions and cyber risks.
- IMF — The World Can't Afford to Get AI Wrong, 15 October 2026 – Managing Director Kristalina Georgieva's discussion of AI investment, productivity, employment, financial stability and cybersecurity.
- IMF — AI and the Global Economy: From Risk to Opportunity, 16 October 2026 – Official description and participants for the wider Annual Meetings discussion of productivity, labour markets, business adoption and financial stability.
- IMF — Artificial Intelligence and Escalating Cyber Risks, 16 October 2026 – Official description and panel participants for the discussion of AI, cybersecurity and financial stability.
- IMF — Fiscal Monitor, October 2026: Taxing Better to Boost Growth – Analysis of tax design, employment incentives, investment, productivity and tax administration.
- IMF and World Bank, with the Bank of Thailand — The Bangkok Blueprint for Fraud-Resilient Financial Services, 14 October 2026 – Policy framework for addressing cyber-enabled fraud through cooperation across financial institutions, technology platforms, telecommunications providers and public authorities.
- Stanford Institute for Human-Centered AI — 2026 AI Index, Economy chapter – Independent research compilation covering AI investment, business adoption, employment, productivity and the changing workplace.
- Stanford Digital Economy Lab — Canaries in the Coal Mine? Six Facts about the Recent Employment Effects of Artificial Intelligence, revised 12 August 2026 – Research using payroll data covering millions of US workers, examining employment patterns among younger workers in AI-exposed occupations.
- National Bureau of Economic Research — Generative AI at Work – Peer-reviewed research examining the effects of generative AI assistance on the productivity of customer-support workers.
Reporting note: The IMF programme descriptions establish the subjects and participants of the Bangkok sessions; they are not verbatim transcripts. Participant names in this article follow the main Annual Meetings schedule on the IMF website as it appeared on 31 October 2026. Not all IMF pages show the same participant lists, and some may have been updated after the meetings. Frettir247 therefore names only participants confirmed in that version and does not add names from earlier or conflicting versions. This report does not present the questions listed in the programme as policy decisions or claim that panellists reached consensus on them. Estimates from research papers and institutional reports are identified as findings or projections, with their limitations explained.
Editorial Note — The New Economy Forum and the Future of the Global Economy
This report examines the technology and economic policy discussions surrounding the New Economy Forum at the October 2026 IMF Annual Meetings in Bangkok.
It focuses on agentic artificial intelligence, tokenised financial infrastructure, taxation, employment, productivity, financial stability and cybersecurity. The aim is to explain how these developments may reshape the relationship between governments, businesses, financial institutions and workers.
The report draws on official IMF programme documents and policy research, including the October 2026 Global Financial Stability Report and Fiscal Monitor. It also incorporates independent evidence from Stanford's 2026 AI Index, research by Stanford's Digital Economy Lab and published academic work on workplace productivity.
Particular care has been taken to distinguish between subjects identified for discussion at the forum, published institutional analysis, independent research findings and possible future developments. Questions raised about AI taxation are not presented as adopted policies, and estimates of future productivity gains are not treated as guaranteed outcomes.
The central issue is how societies can benefit from technological progress while maintaining financial stability, protecting workers, supporting productive businesses and ensuring that the gains are shared more widely.
Frettir247's objective is to make these complex international discussions accessible to readers while retaining the distinctions and qualifications necessary for accurate economic reporting.
Tips, corrections or questions: ritstjorn@frettir247.news
IMF Annual Meetings 2026
- The Global Economy Under Pressure: Growth, Debt, Energy and the Risks Ahead
- Iceland Takes the Floor for Eight Nations: Ásgeir Jónsson Presents Nordic-Baltic Position at IMF Meetings
- Iceland's Economy at a Crossroads: What the IMF Sees Ahead
- The New Economy Forum: How AI Is Reshaping Money, Work and Government
- Iceland's Next Economic Chapter: Building New Industries Beyond Tourism and Fisheries
More from Technology
 TECHNOLOGY · AICan AI Think Like a Supreme Court Justice? University Experiment Tests the Limits of Artificial Intelligence in Law31 October 2026
 TECHNOLOGY · AIArtificial Intelligence and Icelandic Society: Iceland Sets Out Its Priorities30 October 2026
 TECHNOLOGYA Greener Approach to Energy at an Icelandic Riding Hall